
The Precision Castparts valuation debate just received a very large data point. When GE Aerospace announced it would pay $11.75 billion to acquire Consolidated Precision Products (CPP), one of the few meaningful competitors to Berkshire Hathaway’s industrial castings unit, it handed analysts a live comparable transaction with which to reprice a business Warren Buffett once admitted he had overpaid for.
The arithmetic is unflattering for Berkshire’s share price, even if it flatters Buffett’s original conviction.
What the CPP Deal Reveals
GE Aerospace is funding the acquisition with $7 billion in cash and the remainder through new debt, and says the deal does not alter its capital-allocation plans. The company expects the transaction to be accretive to adjusted earnings and free cash flow in its first year, excluding one-time costs. Closing is expected in the second half of 2027, subject to regulatory approvals.
CPP’s sellers are private investment firms Warburg Pincus, which acquired the business in 2011 and manages more than $105 billion in assets, and Boston-based Berkshire Partners, which joined as an investor in a 2019 recapitalisation. For both, the exit represents a premium price: the deal values CPP at roughly 26 times projected 2027 earnings before interest, taxes, depreciation and amortisation, or approximately 18 times including expected net synergies, according to GE Aerospace’s own investor materials.
According to the Wall Street Journal, roughly 60% of CPP’s revenue came from commercial aerospace customers, with defence, power and other markets accounting for the remainder. GE Aerospace, meanwhile, projects that demand for airfoil components will rise more than 30% through 2030 across commercial engines, aftermarket services and defence programmes, a trajectory that explains why it was willing to pay what Quartz describes as the company’s largest acquisition since it became a standalone publicly traded entity.
The Precision Castparts Valuation Gap at Berkshire
Apply that same 26-times multiple to Precision Castparts and Barron’s arrives at a value of around $100 billion for the unit. That is well above the $60 billion to $75 billion range the publication had floated just weeks earlier, when it described the subsidiary as probably one of the more valuable divisions inside Berkshire’s sprawling portfolio.
The gap between what the market appears to be pricing Berkshire at and what Precision Castparts alone might be worth on a standalone basis is the crux of Andrew Bary’s argument in Barron’s. In his view, Berkshire and its share price are not ‘getting much credit’ for the subsidiary’s rising value, partly because chief executive Greg Abel, like Buffett before him, does not hold analyst calls or attend investor events where such figures might receive regular airing.
Bary’s recommendation carries an implicit challenge for the post-Buffett era: ‘Without Warren Buffett at the helm, Berkshire may have to start telling its story if it wants to attract a new generation of investors. This year’s trading action suggests that something may need to change.’
Berkshire’s Class B shares have trailed the S&P 500 by more than 10 percentage points so far in 2026. This week offered a modest reversal, with both share classes gaining nearly 0.9% while the index fell 0.8%, but the year-to-date deficit remains wide.
The Precision Castparts story itself has taken time to turn. Buffett paid $37.2 billion for the business in 2016, an acquisition he later conceded had come at ‘a very high multiple.’ Six years on, Berkshire took an $11 billion write-down, and in his annual letter Buffett acknowledged he had been ‘simply too optimistic’ about the company’s profit potential, a misjudgement compounded by the collapse of aerospace demand during the Covid pandemic.
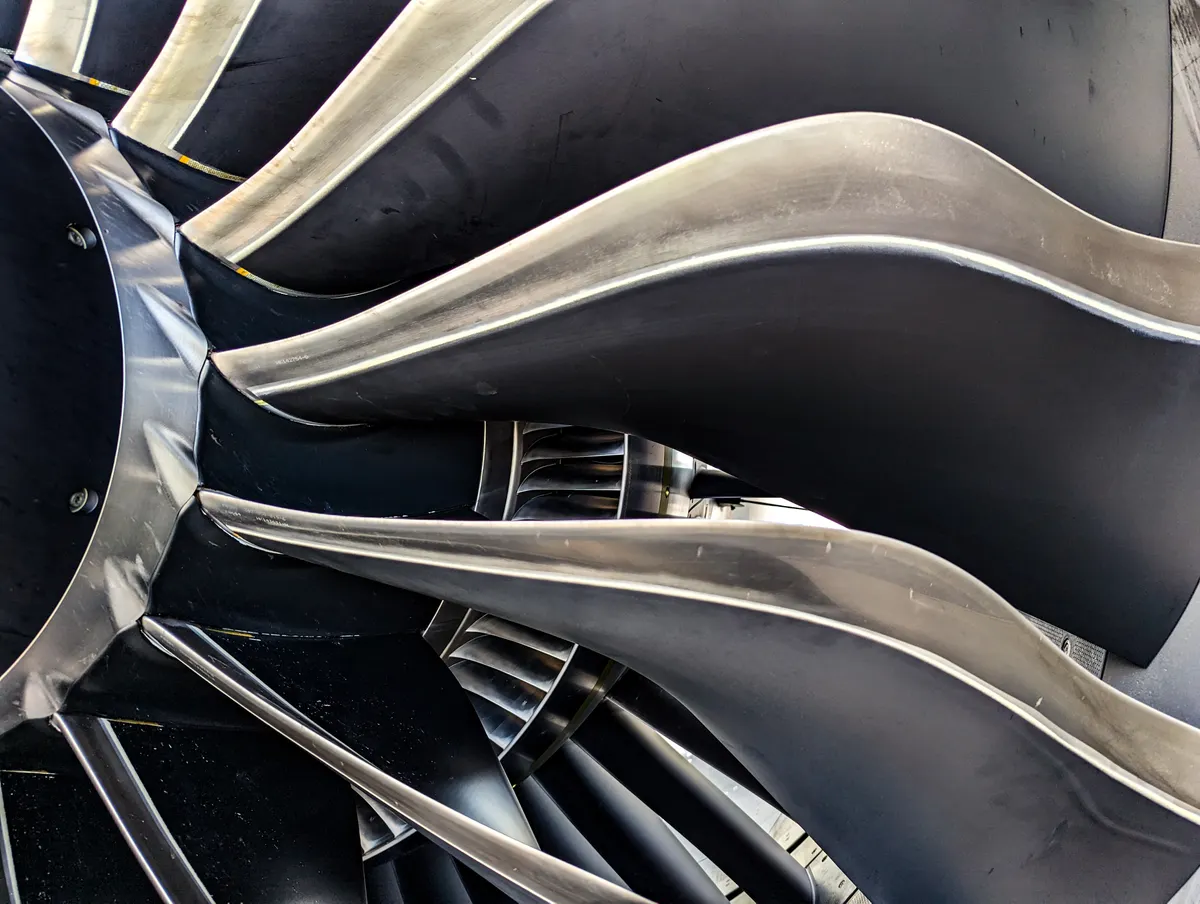
The recovery in that demand, and the new premium placed on precision castings for both jet engine turbine blades and natural gas turbines serving artificial intelligence data centres, has reframed the original thesis. Berkshire’s latest 13F filing, covering the period ending 30 June 2026 and filed with the Securities and Exchange Commission (SEC) on 14 August 2026, disclosed 29 US-listed positions with a total reported portfolio value of approximately $299.25 billion. Precision Castparts, as a wholly owned subsidiary, sits entirely outside that figure.
The Precision Castparts valuation now rests on what Berkshire chooses to do next. If Abel moves toward more active investor communication, the gap between the subsidiary’s implied worth and Berkshire’s traded market capitalisation could narrow. If he does not, the CPP transaction has at least set a public benchmark that analysts will use whether or not Berkshire invites the comparison.